

By Brant Wiehardt EBS CONTRIBUTOR
Sponsored content
Making retirement planning errors at any time, but especially when there’s economic uncertainty and market volatility, can create difficulties in achieving your long-term goals. Here are five common, and potentially costly, mistakes you’ll want to avoid.
1. Getting out of the market after a downturn
When the market takes a big hit, you may be tempted to sell investments in your retirement portfolio and hold the proceeds in cash. If you do, you may miss the gains if the market suddenly turns around.
Consider taking a long-term approach by keeping a strategic mix of asset classes in your portfolio: stocks, bonds, and cash alternatives. The combination that’s right for you will depend on a variety of factors, including how comfortable you are with market volatility (risk tolerance), what you’re investing for (objectives), and how long before you’ll need to tap into your accounts (time horizon).
And think about periodically rebalancing by checking your accounts to see if market activity has shifted your investments away from your desired asset allocation. If it has, you may want to buy and sell investments to bring your accounts back into alignment.
2. Not taking full advantage of retirement accounts
Consider contributing up to the maximum allowable amount into your qualified employer-sponsored retirement plan (QRP), such as a 401(k), 403(b), or governmental 457(b) plan. This can help fund your retirement as well as reduce your taxable income.
If you are unable to contribute the maximum amount and your employer offers a matching contribution, try to contribute at least as much as the match — otherwise, you are leaving free money on the table.
3. Buying too much of your company’s stock
If your employer’s stock is an investment choice in your QRP, give careful consideration to what would be an appropriate amount to own. Company stock can be a good investment when your company does well, but at the same time your salary is already tied to your company’s fortunes. Therefore, it is important to be comfortable with the portion of your retirement savings that will be similarly tied to the success of your company.
4. Borrowing from your retirement plan
Many QRPs offer loans to participants. Unless you need the money for an emergency, consider alternatives before selecting this option. Borrowing can be an expensive choice in two ways:
- Smaller retirement savings: When you take out a loan, you are losing the benefits of potential investment growth on the money you have taken out of the plan, and that could leave you with a smaller retirement savings. Also, if you stop contributing while you are paying back your loan, it may affect employer matching contributions. And keep in mind that the loan, including interest, is paid back with after-tax funds. As a result, these funds are ultimately taxed twice, as these after-tax funds you repay the loan with will be taxed again when you take a distribution from your QRP in the future.
- Repayment requirements: If you leave your employer, the plan may give a short period of time (e.g., 30 or 60 days) to repay that outstanding balance. However, if not repaid, the outstanding loan balance is generally subject to income tax and possibly a 10% additional tax by the IRS on distributions taken before age 59½.
In addition, cashing out of your QRP when you move to a new employer might be costly. Know your distribution options when changing jobs.
5. Underestimating the cost and length of retirement
Some crucial factors to take into account:
- Longevity: If you retire around age 65, you could spend 25 years (or longer) in retirement. As a result, you may need to save enough to last that long, or longer.
- Health care: Even with Medicare, you could have expenses for supplemental insurance, some prescription drugs, and nursing home care.
- Lifestyle sticker shock: Retirees may need approximately 80% of their preretirement income each year.
A financial advisor can help educate you regarding your options so you can decide which ones make the most sense for your specific situation.
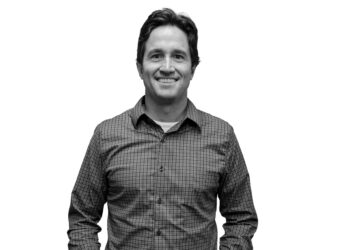
Brant Wiehardt is a Partner and Financial Advisor at Shore to Summit Wealth Management. He currently works and lives in Bozeman, MT with his wife and children.
This article has been prepared for informational purposes only and is not a solicitation or an offer to buy any security or instrument or to participate in any trading strategy. Investing involves risk including the possible loss of principle. Asset allocation cannot eliminate the risk of fluctuating prices and uncertain returns. The accuracy and completeness of this information is not guaranteed and is subject to change. Since each investor’s situation is unique you need to review your specific investment objectives, risk tolerance, and liquidity needs with your financial professional(s) before an appropriate investment strategy can be selected.
Wells Fargo & Company and its affiliates do not provide tax or legal advice. This communication cannot be relied upon to avoid tax penalties. Please consult your tax and legal advisors to determine how this information may apply to your own situation. Whether any planned tax result is realized by you depends on the specific facts of your own situation at the time your tax return is filed.
This advertisement was written by Wells Fargo Advisors Financial Network and provided to you by Brant Wiehardt, Partner, Financial Advisor. Investment products and services are offered through Wells Fargo Advisors Financial Network, LLC (WFAFN), Member SIPC. Shore To Summit Wealth Management is a separate entity from WFAFN.
©2020 – 2026 Wells Fargo Advisors Financial Network, LLC. All rights reserved.