
By Taylor Owens MANAGING EDITOR
Tom has spent 30 years doing everything right. He saved. He stayed out of debt. He showed up every day. And this year, his body started sending him a message his retirement statements couldn’t answer: I can’t keep doing this.
At the kitchen table, his wife Linda spreads out their 401(k) statements, Social Security estimate and savings summary. The numbers are all there. What isn’t there is an answer to the question that matters most: Can we retire?

And if so, when? How much can they spend each year? What happens if one of them lives to 95? What do they even do with their days once they aren’t waking up to go to work?
They have the numbers. What they don’t have is the picture.
Tom and Linda are fictional, a composite created for this story, but the advisors at Stone Leaf Financial say their situation is one they see often. They have saved well, but they don’t know what retirement could look like or how soon they can realistically make the transition.
“The question wasn’t, what’s the market going to do,” one Stone Leaf planner said of a couple like this. “It was, how do we get from where we are today and get you to that next phase of your life comfortably and confidently?”
The truth is that most people retire exactly once.
They get no practice run and no do-over. “Retirement isn’t just a single decision you make at 60 or 65 years old,” one planner said. “It’s a series of decisions.” When to leave work, when to claim Social Security and which accounts to draw from first all come in an order, and that order can matter as much as the decisions themselves.
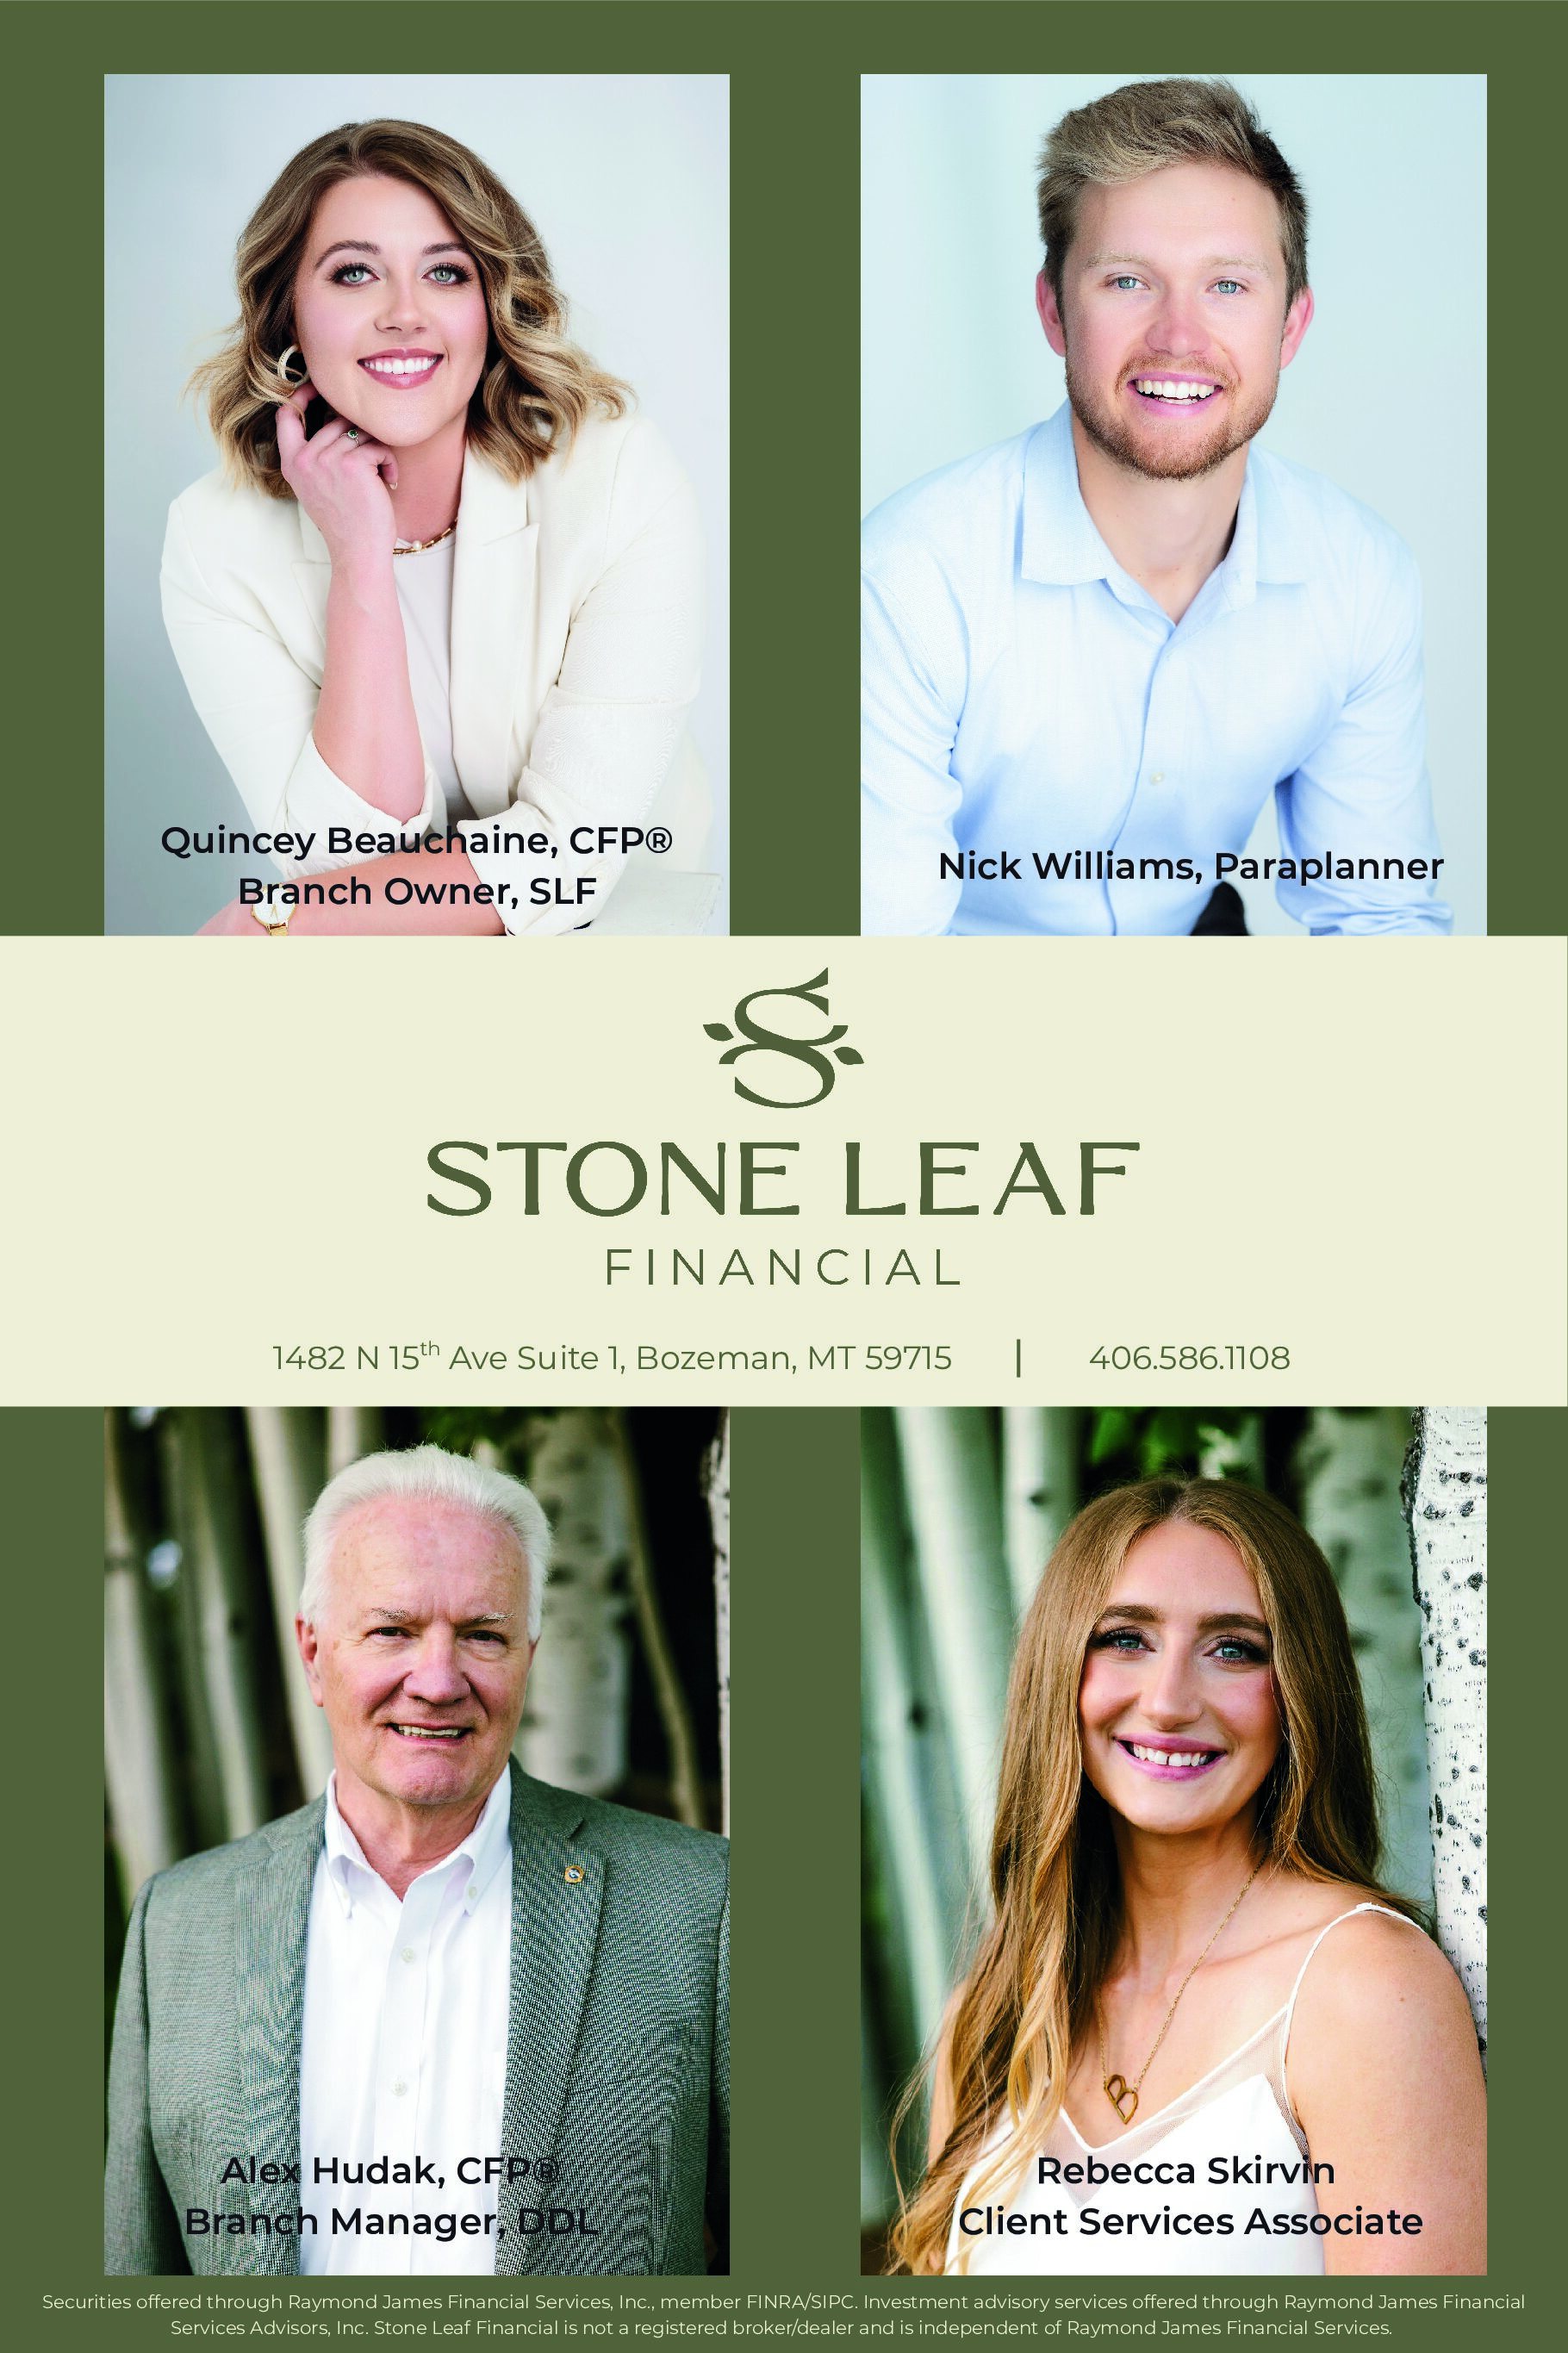
The Stone Leaf team sees it from the other side. “Most people only go through retirement once,” said Nick Williams, paraplanner at Stone Leaf Financial. “We, here as a team, go through retirement weekly with people.”
“For us, planning is very personal,” said Quincey Beauchaine, branch owner at Stone Leaf Financial. “We’re not just looking at someone’s investments when they walk in the door. We want to understand their family, their business, their goals, their concerns, and what they actually want their money to do for them in their retirement years.”
The first meetings are mostly questions. Nothing gets solved in meeting one, and nobody expects it to. The team can point out which statements and documents will be useful along the way. “You don’t need to have anything really together to come and then start an initial conversation with us,” Beauchaine said.
There’s no checklist to push clients through, either. Retirement planning at Stone Leaf is a relationship, and it’s built on knowing people well enough that when the plan meets real life, everyone already knows what matters.
As for the big question of how much is enough: “There’s no magic equation,” Williams said. “I wish there was. It would make life easier.” Everybody spends differently. For some, retirement means traveling every month. For others it’s a quieter, slower life. The team takes in what each person has and what they want. They then use planning software from Raymond James to project out the rest of a lifetime and see whether the money is likely to last under a range of goals and scenarios.
They also build in the things nobody wants to think about, such as living longer than expected or a market downturn. “A good retirement plan isn’t one that only works if everything goes perfectly,” said Rebecca Skirvin, client services associate at Stone Leaf Financial.
Even with a solid plan, the team sees the same pitfalls again and again, in the years just before retirement and the first few years after. Some include spending too much, too fast; playing it too safe; or having nothing to retire to.
Retirement excitement is real and the temptation to spend and enjoy it is as well. On the flip side, retirement can last 30 years. Putting everything into safe investments that don’t grow well over the long haul carries its own risk. Additionally, some people may not have something to retire to. After decades of pouring energy into a career, some retirees find themselves at loose ends. Sometimes a year goes by before they realize they want a part-time job or a new project. The money side of retirement is only half of it. The other half is where you’ll put your time, energy and focus.
The good news is that a plan can bend. If Tom takes a part-time job at 66, his investments may get to keep working a little longer while some income comes in. It’s their plan, and it can shift as they do.
“It’s a very new experience for people, and it can be very scary for them, and it’s very foreign,” Williams said of the first stretch of retirement. People start drawing money from their accounts instead of adding to them, and what they imagined retirement would feel like can look very different after a year of living it.
So the Stone Leaf team stays in close contact during those early years. They check in often, keep the withdrawals tax-efficient, reassure when reassurance is needed and adjust when something changes. And when the unexpected happens, they aren’t starting from scratch. They already know the person and the big picture.
If you’re 60 and feeling behind, it’s not too late. You’ve spent 30 or 40 years building a financial life, and much of the work now is making all of it fit together in a way that works for you. The team has worked with people of every age. “The earlier the better,” Beauchaine said, “but the second-best time is today.”
And if you’ve done it all yourself and feel good about it, a second opinion is still worth having. It’s a big decision.
The Stone Leaf team’s message comes down to one idea. “The hard part isn’t necessarily saving for retirement, it’s knowing what to do next,” Beauchaine said. Confidence in that next stage comes from talking to people and saying it out loud. “Whether that be with us or another advisor, it is worth the conversation.”
To start the conversation, contact Stone Leaf Financial at 406-586-1108 or at stoneleaffinancial.com.
Hypothetical examples are for illustration purposes only.
Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional. Investment advisory services offered through Raymond James Financial Services Advisors, Inc. Stone Leaf Financial is not a registered broker/dealer and is independent of Raymond James Financial Services. Securities offered through Raymond James Financial Services, Inc., member FINRA / SIPC.